This Week at a Glance
US inflation ran hot on both fronts: CPI rose to 3.7%,
and producer prices jumped 6.3%, the fastest since 2022. Yet the Dollar ended a four-week winning streak after Fed Chair Warsh refused to pre-commit to an October hike.
WTI broke back above $100 with an 8% weekly surge, while tech stocks dragged the S&P 500 down 2%.
With the Fed in blackout, the spotlight moves to UK jobs and inflation, China's Q3 GDP, flash PMIs and big tech earnings.
Last Week's Scoreboard
Instrument | Price | Weekly Change |
|---|---|---|
DXY | 101.46 | ▼ 0.43% |
EUR/USD | 1.1240 | ▲ 0.34% |
GBP/USD | 1.3328 | ▲ 0.72% |
Gold | 4,165.82 | ▼ 0.70% |
WTI | 100.96 | ▲ 8.32% |
US500 | 7,655.28 | ▼ 2.01% |
BTC/USD | 81,155 | ▼ ~2% |
Key Events This Week (GMT)
Day | Time | Event | Forecast / Prior | Impact |
|---|---|---|---|---|
Mon 19 Oct | 02:00 | China Q3 GDP, Retail Sales, Industrial Production | – | ★★★ |
Tue 20 Oct | 06:00 | UK Labour Market Report | – | ★★★ |
Tue 20 Oct | 09:00 | Germany & Eurozone ZEW Sentiment | – | ★★ |
Tue 20 Oct | 12:30 | US Housing Starts | 1,250K exp. | ★ |
Wed 21 Oct | 06:00 | UK CPI (Sep) | – | ★★★ |
Wed 21 Oct | 07:20 | Bank Indonesia Rate Decision | 75 bps hike exp. | ★★ |
Wed 21 Oct | 12:30 | Canada CPI (Sep) | – | ★★ |
Thu 22 Oct | 12:30 | US Initial Jobless Claims | – | ★ |
Thu 22 Oct | 14:00 | Eurozone Flash Consumer Confidence | – | ★ |
Thu 22 Oct | 23:30 | Japan CPI (Sep) | – | ★★ |
Fri 23 Oct | 06:00 | UK Retail Sales | – | ★★ |
Fri 23 Oct | 07:30–08:30 | Flash PMIs: Germany, Eurozone, UK | – | ★★★ |
Fri 23 Oct | 13:45 | US Flash S&P Global PMIs | – | ★★★ |
Time zones: London is GMT+1 (BST until October 25), New York GMT−4, Singapore/Hong Kong GMT+8.
Earnings to watch include Tesla, Netflix, Lam Research, Western Digital, Procter & Gamble and American Express. The Fed is in its blackout period ahead of the October 27–28 meeting. BoE Governor Bailey (Wednesday, Thursday) and ECB President Lagarde (Wednesday) are among the speakers.
Market Sentiment Overview
Inflation data came in hot, but markets ended the week calmer than they started. US CPI rose to 3.7% y/y with core at 2.6%, while PPI jumped 1.3% m/m, driven by energy and a 21% monthly surge in diesel. Retail sales beat at 0.8%, but most of the gain came from fuel; the control group rose only 0.14%. October hike odds briefly spiked after CPI, then collapsed to around 10–16% after Warsh said decisions will be made meeting by meeting. December remains the base case, priced near 80%. Treasury yields fell from multi-decade highs toward 5% as tech stocks slid and investors sought safety in bonds. The Middle East remains a constant risk, with oil back above $100 and fresh Houthi attacks on Saudi Arabia.
Currencies
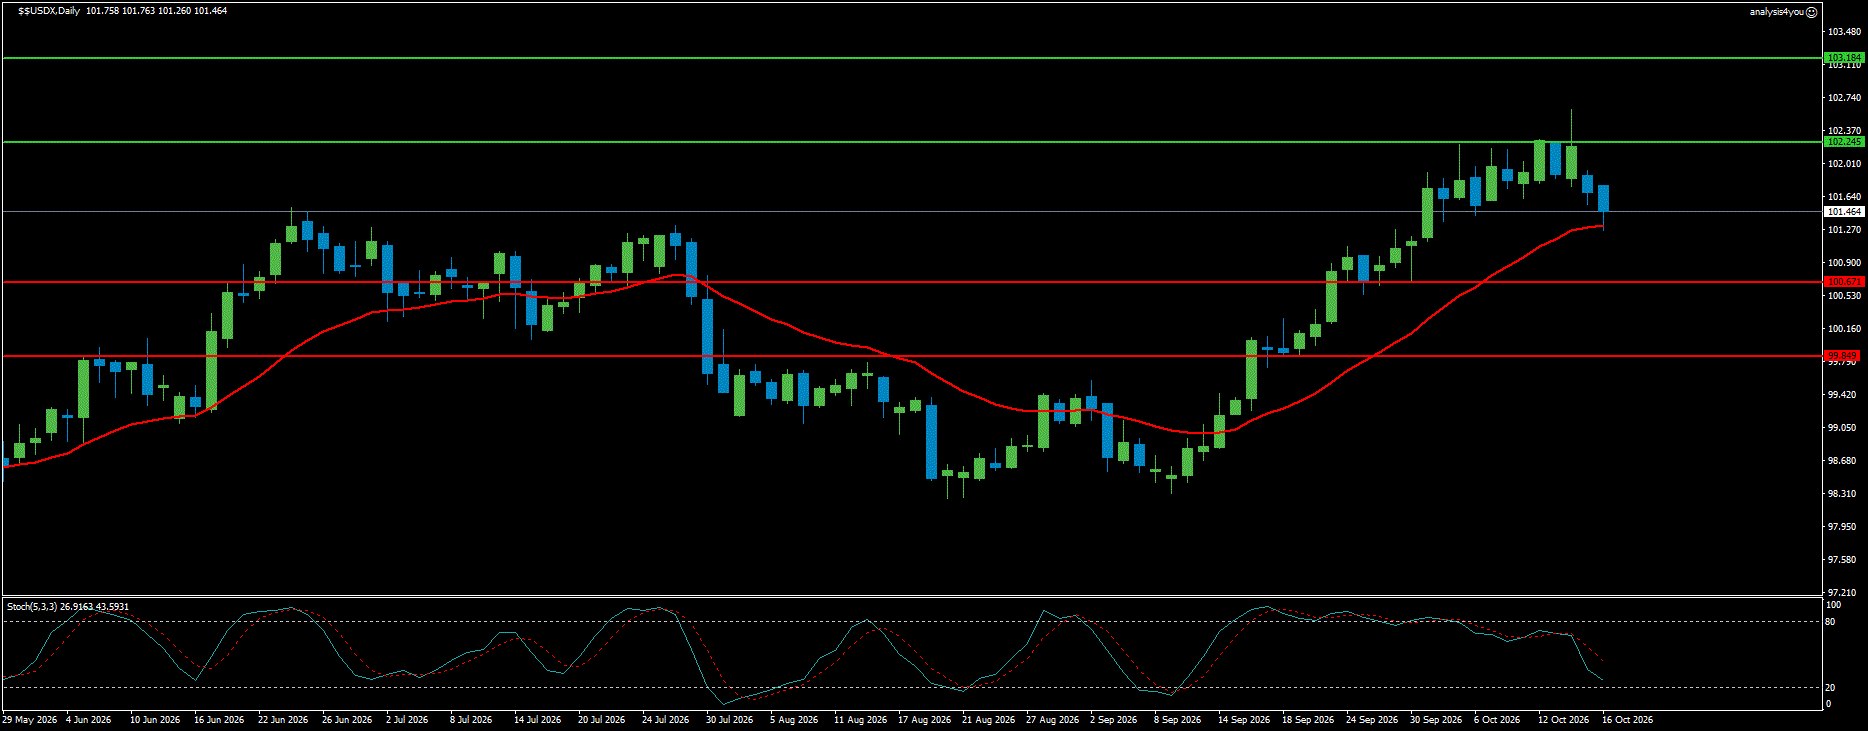
USD Index (DXY): A Pause, Not a Reversal (101.46)
Trend: Bullish | Sentiment: Mixed
The Dollar Index came close to 103.00 after the hot CPI print, then reversed to two-week lows, ending four straight weekly gains. The pullback looks more about sentiment than fundamentals. Warsh's non-committal tone and falling Treasury yields did the damage, while inflation and the Fed's tightening bias are unchanged. Hammack, Collins, Daly and Musalem still argue for more hikes, though Williams and Goolsbee urged patience. Speculative positioning is neutral, which leaves room for fresh buying if data supports the hike case. Price is now testing the rising 20-day MA.
Resistance: 102.25; 103.18 | Support: 100.67; 99.85
Bias: Holding the 20-day MA keeps the uptrend intact, with a move above 102.25 reopening 103.18. A close below 100.67 would signal a deeper correction toward 99.85.
EUR/USD: First Weekly Gain, but Sellers Still in Control (1.1240)
Trend: Bearish | Sentiment: Negative
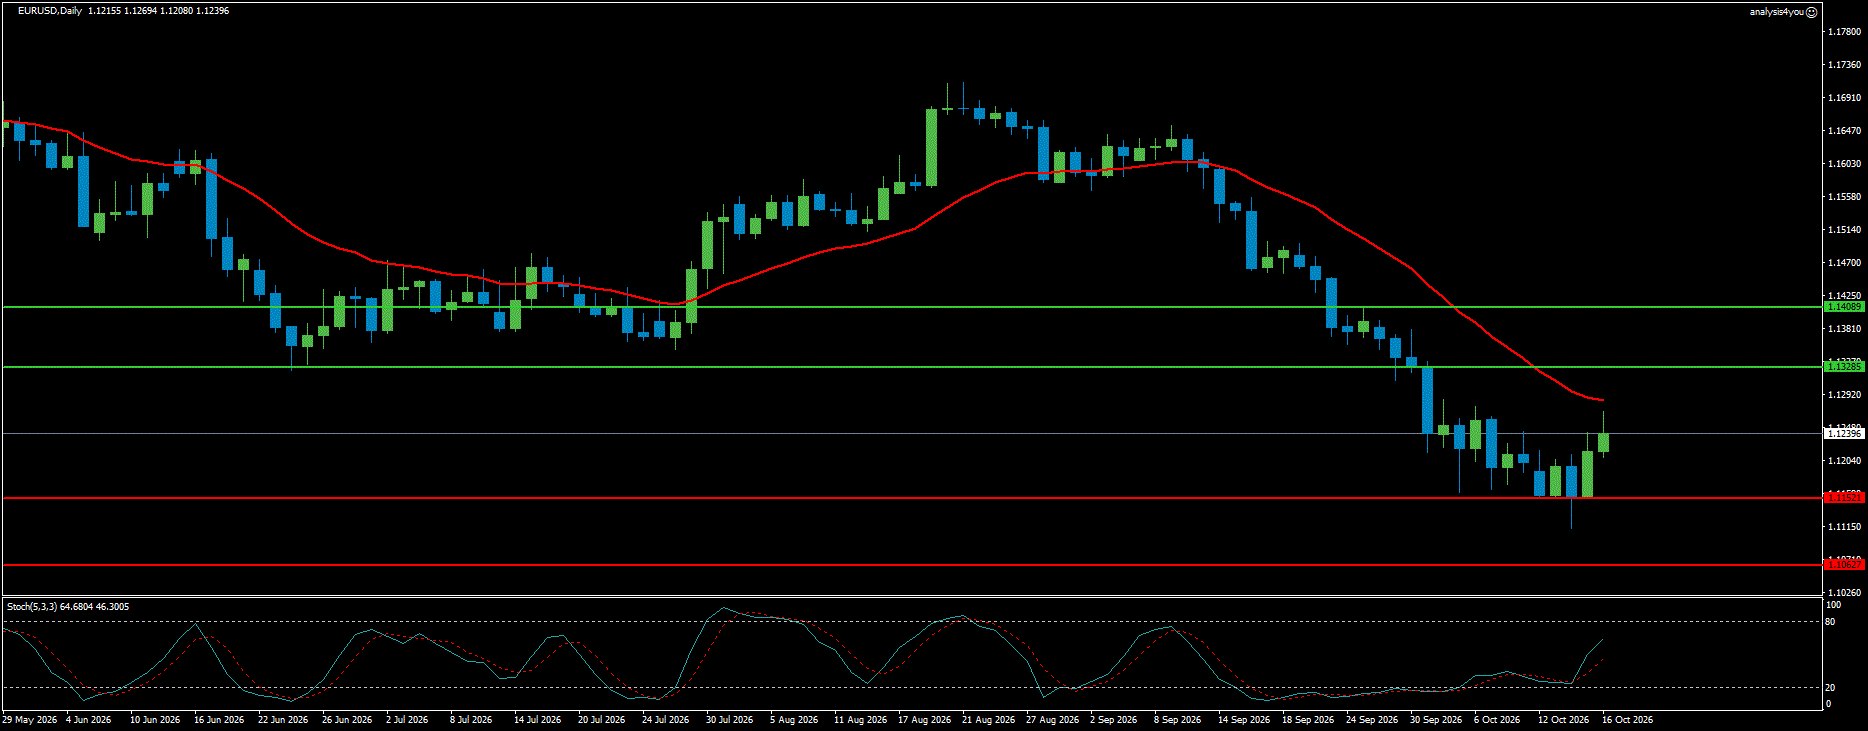
The Euro hit a fresh 2026 low at 1.1113 before bouncing, posting its first weekly gain after five straight losses. The recovery was driven by Dollar weakness rather than European strength. Eurozone inflation reached 3.8%, a three-year high, and Lagarde signaled the ECB won't wait for second-round effects to be fully visible, but her hawkish words failed to lift the Euro. French fiscal risk and talk of ECB bond buying still weigh on the currency. Price remains below the falling 20-day MA, which caps the rebound.
Resistance: 1.1328; 1.1409 | Support: 1.1152; 1.1063
Bias: The bounce looks corrective while below 1.1328. A break under 1.1152 reopens the yearly low and 1.1063. Friday's PMIs are the main test.
GBP/USD: Sterling Stages a Bullish Reversal (1.3328)
Trend: Neutral | Sentiment: Positive
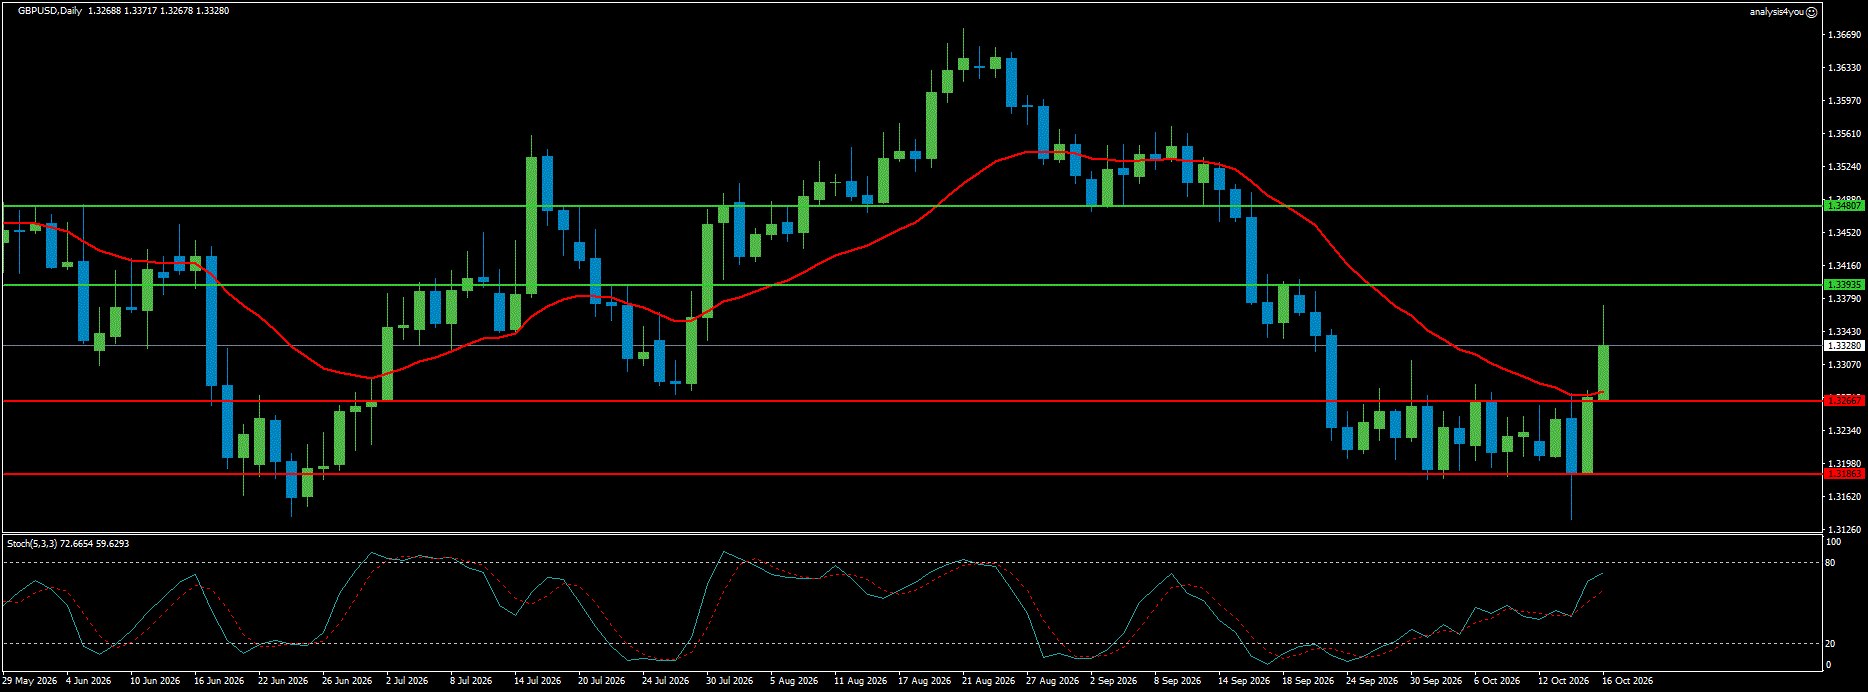
Sterling ended four weeks of losses with a strong rebound from Wednesday's post-CPI low, closing back above 1.3300 and reclaiming its 20-day MA. Scotiabank notes a major bullish outside range forming on the weekly chart, with the pair basing near the bottom of a range in place since April. Governor Bailey said the UK economy is more resilient than expected, and swaps remain almost fully priced for a 25 bps hike on November 5. The Pound is also outperforming the Euro, helped by closer UK–EU ties. This week's jobs, CPI and retail sales data will test those hike bets.
Resistance: 1.3394; 1.3481 | Support: 1.3267; 1.3186
Bias: A break above 1.3394 opens 1.3481, with the range top at 1.3650–1.3675 as the bigger target. Holding 1.3267 keeps the recovery on track, and a soft UK CPI is the main risk.
Commodities
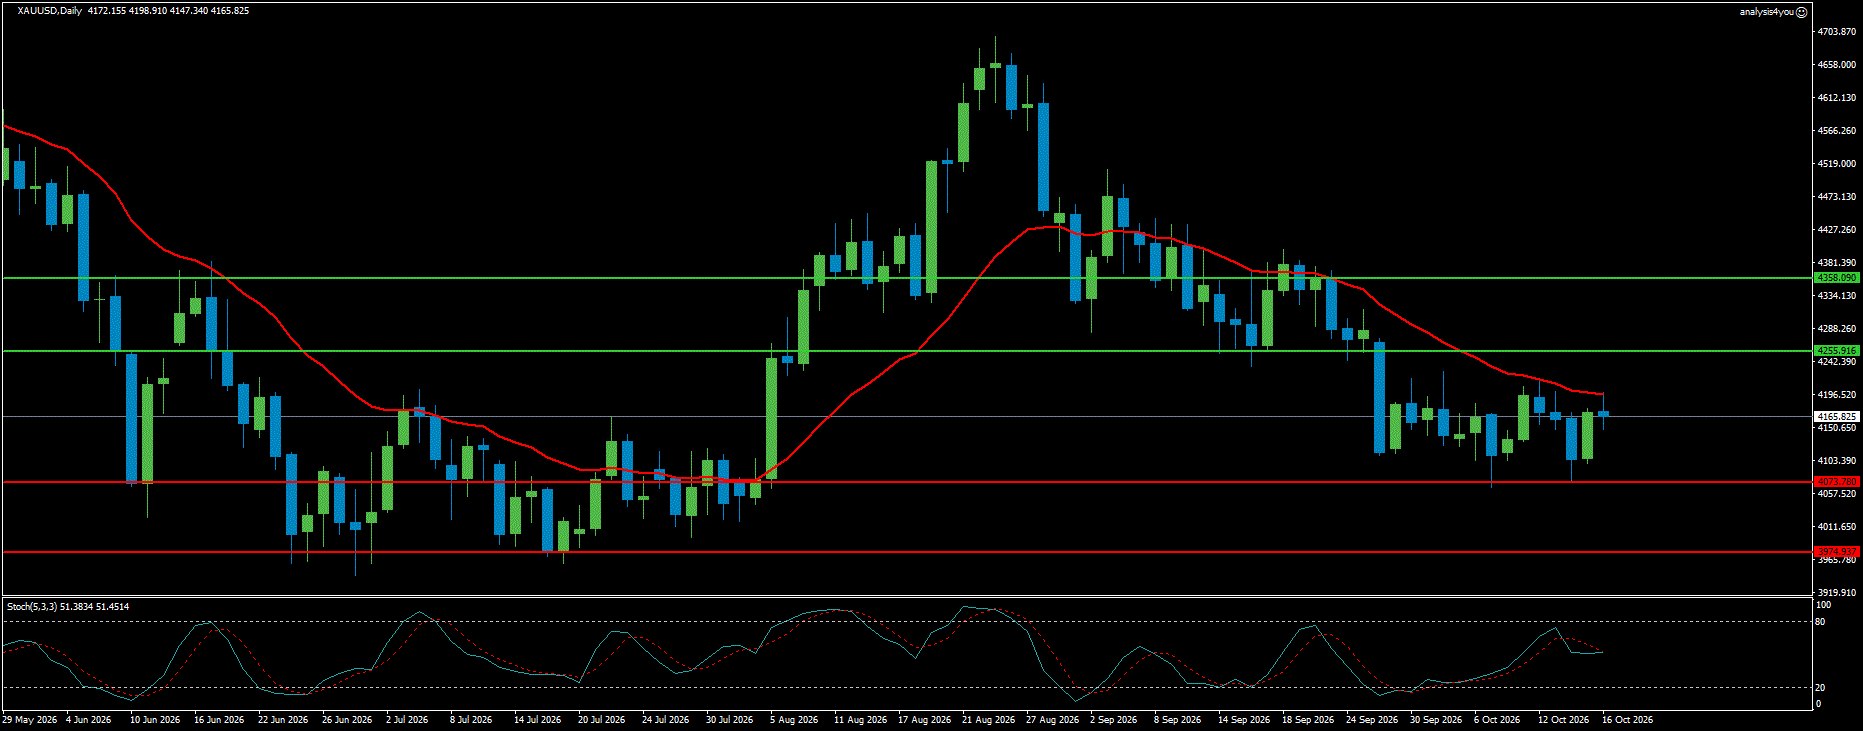
Gold: Trading the Bond Market, Not the Data (4,165.82)
Trend: Bearish | Sentiment: Mixed
Gold fell more than 1% on Wednesday's hot CPI, briefly dipping toward $4,073, then rallied 1.6% on Thursday as Treasury yields dropped sharply. A Bloomberg report that China is shifting US securities to non-US custodians added to the bond market debate, and Warsh's speech extended the recovery toward $4,200, though Gold still ended the week slightly lower. TD Securities expects strong flows from ETFs and central banks to support Gold in the $4,000–$4,100 region. OCBC cautions that the rebound is driven by the bond market's reaction rather than improving inflation, which makes it fragile. Price remains below the 20-day MA, which keeps capping recovery attempts.
Resistance: 4,255.92; 4,358.09 | Support: 4,073.78; 3,974.94
Bias: A daily close above 4,256 would open 4,358. Losing 4,074, which has held twice this month, would expose 3,975.
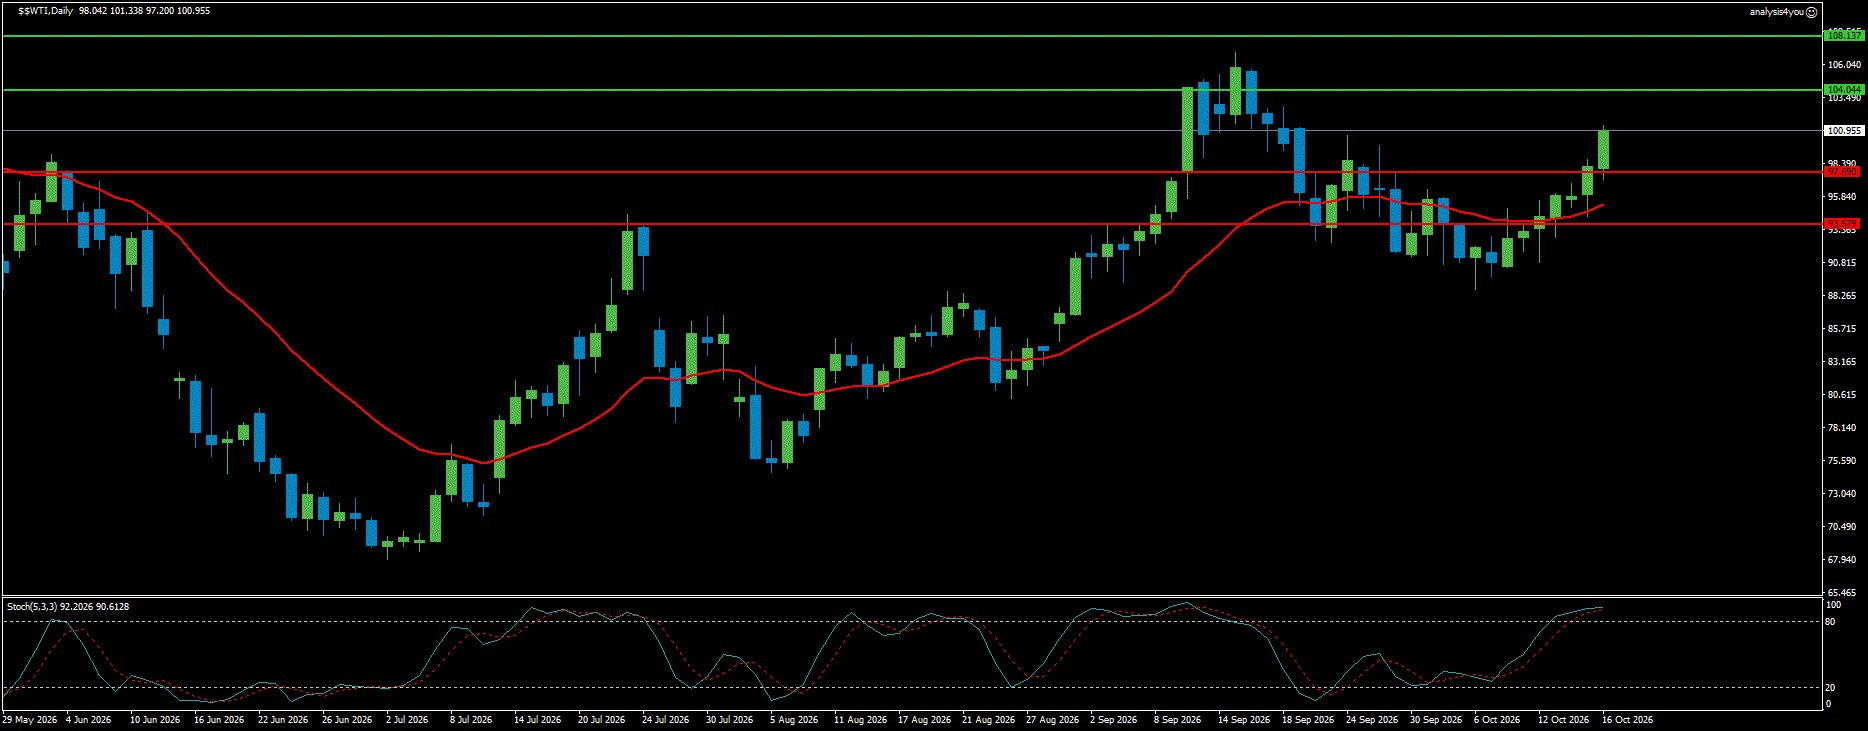
WTI Crude Oil: Diesel Becomes the Inflation Story (100.96)
Trend: Bullish | Sentiment: Mixed
WTI surged more than 8% this week and broke back above $100. Supply from the Gulf is slowly improving, but there is no progress in US–Iran talks. Houthi attacks on Saudi Arabia, new US sanctions on Iran, and Trump's threat of heavy strikes after the November 3 midterms keep the risk premium high. Refined products are the real pressure point: diesel prices jumped 21% in September, and the Fed's Beige Book found that higher oil prices showed up in every district. Price is trading above its upper Bollinger Band with the Stochastic overbought, so a pause is possible after such a sharp move.
Resistance: 104.04; 108.14 | Support: 97.69; 93.68
Bias: Holding 97.69, the breakout level, keeps the uptrend intact toward 104.04 and 108.14. Any concrete Hormuz deal is the main downside risk.
Stocks & Indices
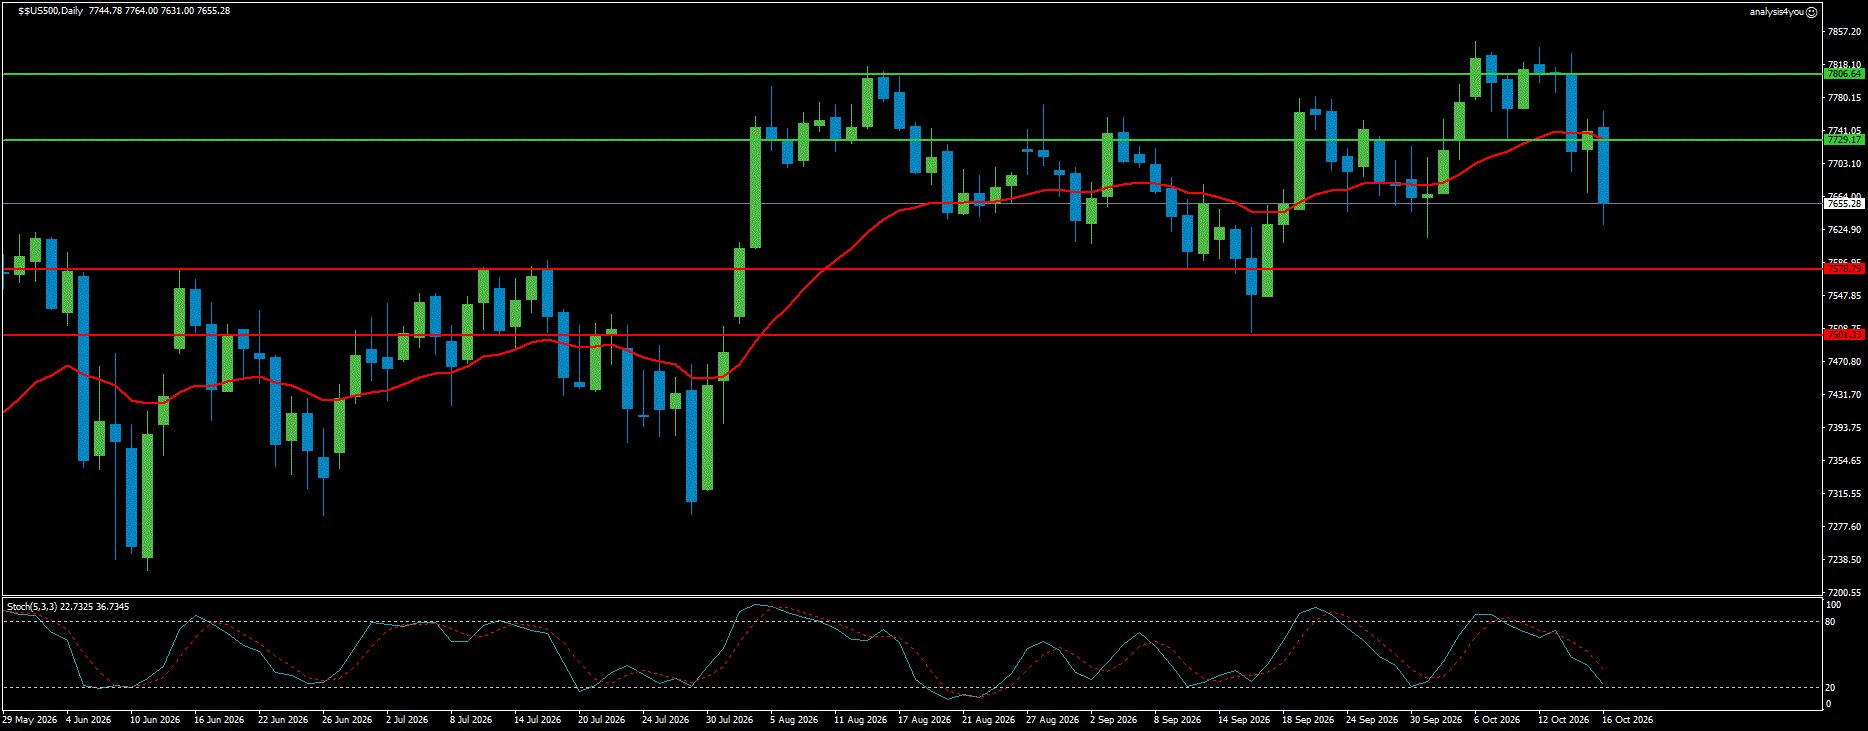
US500: Tech Cracks Under the AI Bill (7,655.28)
Trend: Bullish | Sentiment: Negative
The S&P 500 fell about 2% as tech stocks posted a second straight weekly loss, the first such run since March. Banks and AI-related names like TSMC delivered solid results, but investors grew uneasy about whether huge AI spending can stay profitable with higher inflation and rates. Breadth was already weak, so the index depends heavily on mega-cap tech. Friday's large bearish candle closed below the 20-day MA. Earnings from Tesla, Netflix and Lam Research this week will test tech leadership, and with the midterms 20 days away, polls suggest Democrats could retake the House.
Resistance: 7,729; 7,806.64 | Support: 7,578.79; 7,501.33
Bias: Reclaiming 7,729 would ease pressure. A break below 7,579 opens 7,501, and continued tech weakness could trigger a wider sell-off given heavy investor exposure.
Cryptocurrencies
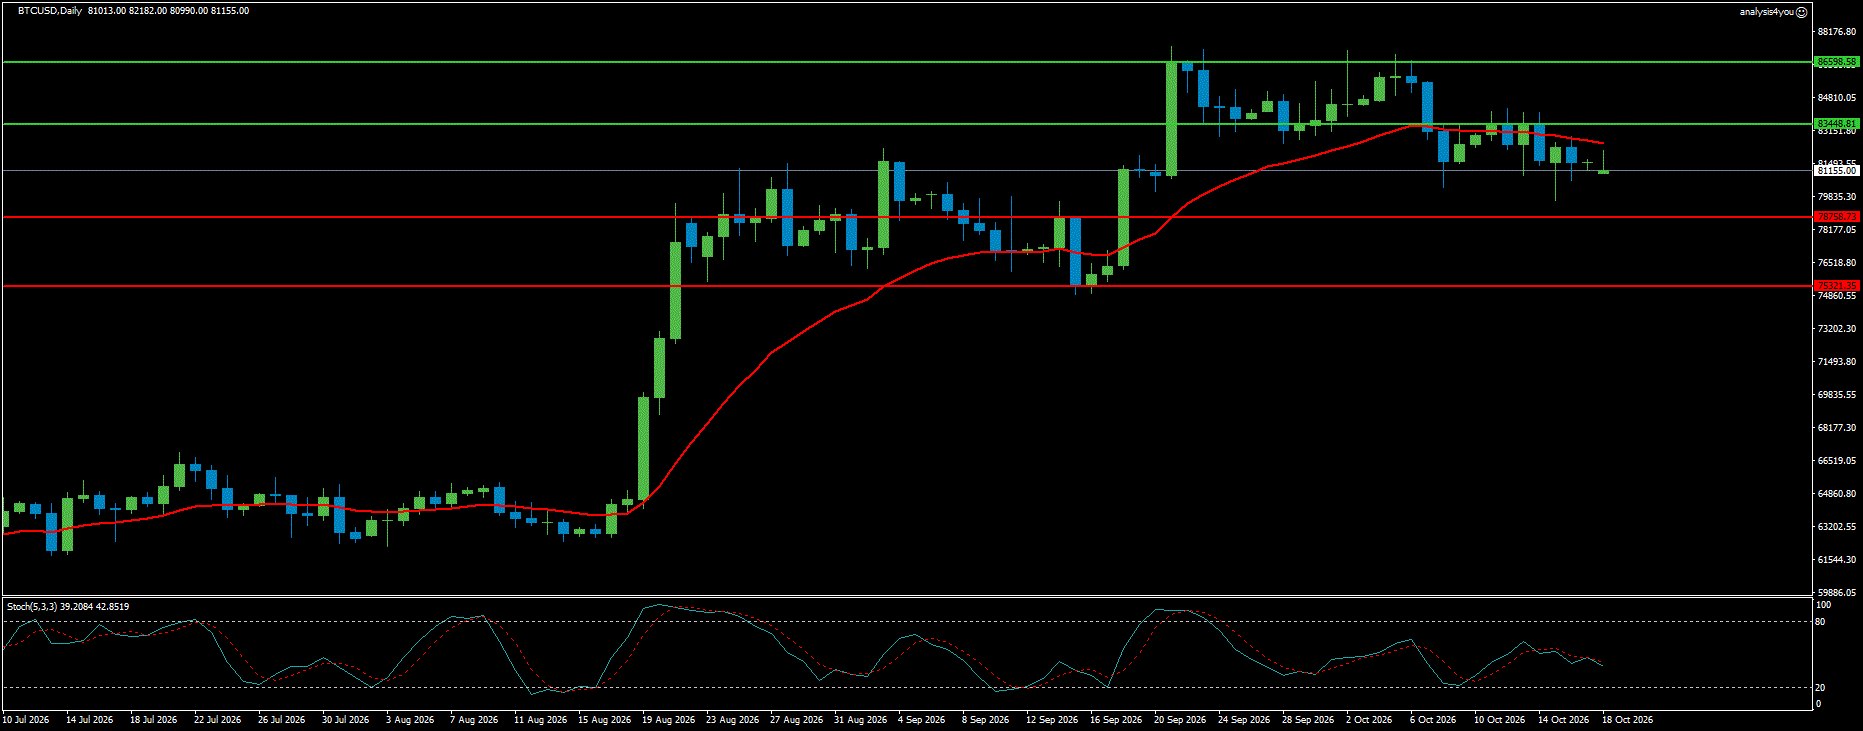
Bitcoin: Uptober Loses Its Spark (81,155)
Trend: Bullish | Sentiment: Negative
Bitcoin fell for a second straight week, briefly dropping below $80,000 before recovering. Spot ETFs are on track for a second week of outflows, with $146 million withdrawn through Thursday, and hot inflation data plus Middle East escalation weighed on risk appetite. Corporate buyers keep accumulating: Strategy added 250 BTC and Strive bought 3,311 BTC. CryptoQuant's analyst consensus index is strongly bullish, with 84% of analysts positive. Price has slipped below its 20-day MA, though the broader uptrend from August is still intact.
Resistance: 83,448.81; 86,598.58 | Support: 78,758.73; 75,321.35
Bias: A recovery above 83,449 would revive the Uptober case and open 86,599. Losing 78,759 would expose the 75,321 area.
Week Ahead Outlook
UK data (Tuesday–Friday): The jobs report, CPI, and retail sales will decide whether the November BoE hike stays locked in. Strong numbers would extend the Pound's recovery, while a sharp drop in core inflation could make BoE doves more vocal.
China GDP (Monday): Strong data would support AUD and risk sentiment after a 4.5% slide in AUD/USD since early September.
Flash PMIs (Friday): These are the week's main global data point. Weak Eurozone numbers would add pressure on the Euro. US PMIs only matter if they surprise by dropping below 50.
Oil, earnings and yields: With the Fed silent, oil above $100 is the biggest inflation risk. Tech earnings and Treasury yields will drive the Dollar, Gold and equities. Further declines in yields would support Gold, while a rebound would revive Dollar demand.
The Fed meets in under two weeks, and the market is still deciding between December and later. Stay patient: the goal is always to get profit, not to trade as many as possible.
Disclaimer: This analysis is for educational and informational purposes only and does not constitute investment advice. Trading leveraged products such as Forex, Gold, commodities, indices and cryptocurrencies carries a high level of risk and may not be suitable for all investors.